The Hackett Group® Finds Record $1.94 Trillion Working Capital Opportunity Among North America’s Largest Companies
2026 Working Capital Survey reveals strong financial performance is masking growing cash inefficiencies, with

Press Release Disclaimer: This is a press release distributed through the XPR Media network. It has not been independently verified by our newsroom.

The Hackett Group, Inc. (NASDAQ: HCKT), an AI enterprise transformation firm, today announced findings from its 2026 North American Working Capital Survey, revealing that the 1,000 largest public companies in North America hold a record $1.94 trillion working capital management opportunity – up 12% from the prior year. The findings show that while companies delivered strong revenue growth, profitability and operating cash flow in 2025, significantly more cash became tied up in working capital, particularly in receivables.
This press release features multimedia. View the full release here: https://www.businesswire.com/news/home/20261005654787/en/
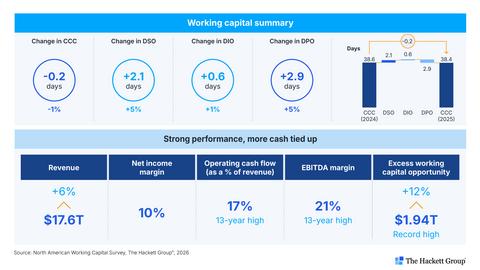
By most measures, the 1,000 largest North American public companies had a strong year. The Hackett Group’s 2026 North American Working Capital Survey found revenue up 6% to $17.6 trillion, while net income margin reached 10%. Operating cash flow rose to 17% of revenue and earnings before interest, taxes, depreciation and amortization (EBITDA) margin to 21% – each its strongest level in 13 years. Stronger profits came with more cash tied up for every dollar of revenue. The excess working capital opportunity climbed 12% to a record $1.94 trillion. The cash conversion cycle (CCC) shows how that deterioration stayed partially hidden. CCC improved by just 0.2 days, with the entire gain coming from one place. A 2.9-day improvement in days payable outstanding (DPO) narrowly offset deterioration in receivables (+2.1 days) and inventory (+0.6 days). Receivables are now the largest and fastest-growing component of the opportunity at $773 billion.
The survey found that revenue increased 6% to $17.6 trillion, operating cash flow reached a 13-year high at 17% of revenue and EBITDA (earnings before interest, taxes, depreciation and amortization) margins rose to 21%. Yet excess working capital relative to revenue increased, reversing three consecutive years of improvement and reaching its highest level on record.
“The headline numbers suggest many organizations had a very successful year, but a closer look shows a different story,” said Gerhard Urbasch, associate principal at The Hackett Group®. “Companies generated strong growth and profits, yet more cash became trapped in the processes that convert revenue into cash. Receivables have become the largest and fastest-growing source of working capital inefficiency, and the data shows that sustainable improvement requires a broader focus on how revenue becomes cash, not just isolated initiatives aimed at collections or payment terms.”
Although the overall cash conversion cycle (CCC) improved slightly, declining 0.2 days to 38.4 days, the improvement was driven entirely by stronger payables performance. Days sales outstanding (DSO) deteriorated sharply by 2.1 days, and days inventory outstanding (DIO) increased by 0.6 days, while days payable outstanding (DPO) improved by 2.9 days. As a result, gains in payables offset deterioration elsewhere in the cycle rather than reflecting broad-based improvement.
Receivables emerged as the largest and fastest-growing source of working capital inefficiency. The accounts receivable opportunity increased 29% year over year to $773 billion, representing 40% of the total working capital opportunity. DSO worsened for the third consecutive year and deteriorated in 40 of 50 industries analyzed. Aggregate receivables grew 11%, nearly twice the pace of revenue growth.
Receivables performance issues often originate long before an invoice becomes overdue. According to the survey, credit decisions, negotiated payment terms, order accuracy, billing quality, dispute management and cash application all influence how quickly revenue is converted into cash. The findings suggest that organizations taking an end-to-end process approach are better positioned to improve working capital performance than those focused solely on collections.
Inventory also contributed to the growing opportunity. The inventory opportunity rose 6% to $616 billion as organizations continued carrying buffer stock to manage tariff exposure, supply chain uncertainty and sourcing diversification efforts. The findings indicate many companies are prioritizing resilience and supply assurance, even when doing so increases balance sheet intensity.
Meanwhile, payables represented the strongest area of performance improvement. The payables opportunity remained relatively stable at $548 billion, while DPO reached its best level since 2021. Supply chain finance activity increased significantly, with settlement volumes rising 35% year over year. However, the report concludes that extending payment terms alone is unlikely to provide a sustainable path to future improvement.
The survey also highlights how difficult it is to sustain progress over time. Of the 1,000 companies analyzed, only 98 improved their cash conversion cycle for three consecutive years, just nine sustained improvement for five years and only two organizations achieved seven straight years of improvement.
According to The Hackett Group®, the findings underscore an emerging opportunity for process-led artificial intelligence (AI). The firm’s AI World Class benchmark research shows significantly stronger results among organizations that redesign workflows around AI-enabled decision-making, automation and exception handling. Compared with peers, AI World Class order-to-cash organizations demonstrate 138% more automated credit decisions, 134% greater digital order intake, 89% more automated cash application and 85% fewer delinquent days.
“The working capital challenge is increasingly becoming an AI opportunity,” said Kathleen Wiedeman, senior director at The Hackett Group®. “Leading organizations are not simply applying AI to existing processes. They are redesigning end-to-end workflows across order-to-cash, forecast-to-fulfill and purchase-to-pay. That’s where we see the greatest potential to improve cash flow, increase productivity and sustain performance gains over time.”
The Hackett Group’s 2026 North American Working Capital Survey analyzes the latest publicly available FY2025 financial results of the 1,000 largest nonfinancial companies headquartered in North America and evaluates performance across receivables, inventory and payables.
Download the full results and insights from the 2026 North American Working Capital Survey for free with registration.
About The Hackett Group®
The Hackett Group, Inc. (NASDAQ: HCKT) is an ROI-led, AI enterprise transformation firm that helps clients enable AI World Class performance. Its experts and engineers leverage Hackett AI platforms, including XT™, AIXelerator™, Hackett AI XPLR™, ZBrain® and XDA™, to accelerate and enhance the delivery of the company’s solutions and services.
The Hackett AI platforms are powered by the company’s domain-specific Solution Language Model informed by Hackett Process and Performance Intelligence, including Digital World Class® and AI World Class benchmark metrics, industry-specific best-practice process flows and service delivery model frameworks. The Hackett Group’s proprietary insights are based on benchmarking results from leading global organizations, including 98% of Dow Jones Global Titans, 97% of the Dow Jones Industrials and 90% of the Fortune 100. Visit www.thehackettgroup.com.
Trademarks
The Hackett Group®, quadrant logo, ZBrain® and Digital World Class® are the registered marks of The Hackett Group®.
Cautionary Statement Regarding “Forward-Looking” Statements
This release contains “forward-looking” statements within the meaning of Section 27A of the Securities Act of 1933 as amended and Section 21E of the Securities Exchange Act of 1934, as amended. Statements including without limitation, words such as “expects,” “anticipates,” “intends,” “plans,” “believes,” “seeks,” “estimates,” or other similar phrases or variations of such words or similar expressions indicating, present or future anticipated or expected occurrences or outcomes are intended to identify such forward-looking statements. Forward-looking statements are not statements of historical fact and involve known and unknown risks, uncertainties and other factors that may cause the Company’s actual results, performance or achievements to be materially different from the results, performance or achievements expressed or implied by the forward-looking statements. Factors that may impact such forward-looking statements include without limitation, the ability of The Hackett Group® to effectively market its digital transformation services, our ability to transition our capabilities to support generative artificial intelligence (AI)-related consulting services and solutions and other consulting services, our ability to effectively integrate acquisitions into our operations, our ability to manage joint ventures and successfully cooperate with our joint venture partners, competition from other consulting and technology companies that may have or develop in the future, similar offerings, the commercial viability of The Hackett Group® and its services as well as other risk detailed in The Hackett Group’s reports filed with the United States Securities and Exchange Commission. The Hackett Group® does not undertake any duty to update this release or any forward-looking statements contained herein.
View source version on businesswire.com: https://www.businesswire.com/news/home/20261005654787/en/
Media gallery